
How to File a Roofing Insurance Claim: A Step-by-Step Guide
A roof claim is paperwork plus evidence plus timing. Follow the same sequence adjusters and contractors use — document, file, meet, review, supplement — and you keep control of both the repair and the payout.
Quick Answer — The Claim Sequence
- Keep everyone safe and stay off a damaged roof; contain water from inside.
- Tarp to prevent more damage, save every receipt — mitigation is covered under most policies.
- Photograph everything before touching it, then file promptly with your insurer.
- Meet the adjuster with your own contractor present and compare the scope of loss against real estimates.
- Supplement for missed items, choose your own contractor, and track depreciation release on RCV policies.
What Should You Do Immediately After Roof Damage?
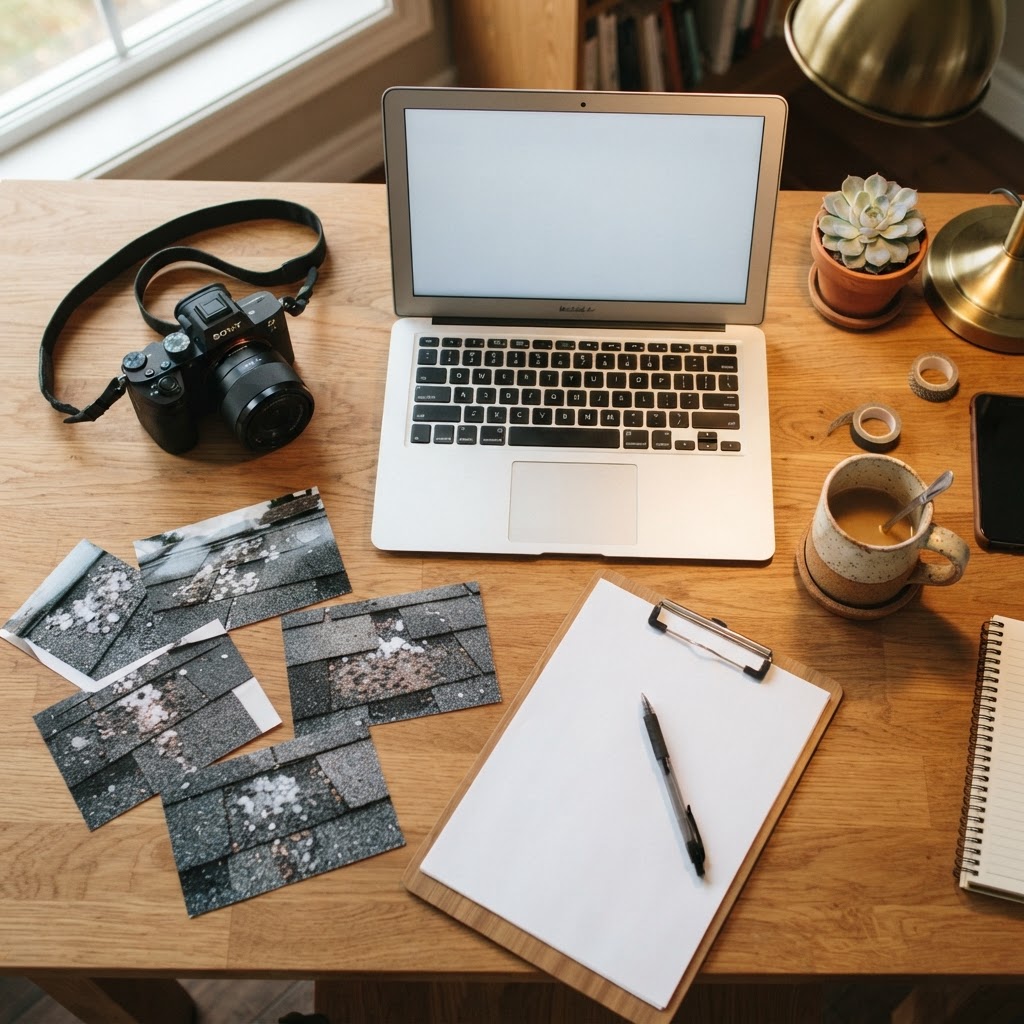
The hours right after a storm set the tone for the entire claim. Safety comes first: downed power lines, unstable gutters, and a slippery, punctured deck make a damaged roof genuinely hazardous, so nobody should climb up to “take a quick look.” From the ground, photograph and video the whole house before touching anything, because the evidence you capture today supports every number in the claim later. Water coming inside gets contained with buckets and moved valuables, not by a homeowner scrambling onto wet shingles.
The first day should follow a short, disciplined list:
- Confirm everyone is safe and keep clear of downed lines, hanging limbs, and unstable debris
- Photograph and video the exterior from the ground before moving or covering anything
- Make temporary repairs — tarps, boarded openings, shut-off utilities — to stop ongoing damage
- Save every receipt for tarps, lumber, generators, and lodging, because mitigation costs are usually covered
- Call your insurer’s claim line, get a claim number, and write down the date and representative’s name
- Schedule an inspection with a local contractor you choose yourself
Two habits pay off disproportionately here. Mitigation is your responsibility under most policies, and insurers reimburse reasonable emergency repairs when receipts document them — a $200 tarp job that saves a soaked attic is money spent exactly right. Save damaged shingle pieces and dislodged flashing in a bag, because physical samples are the strongest evidence a claim file can hold.
How Do You Document Roof Damage for a Claim?
Claims are won with evidence, and evidence has a shelf life. Rain washes granule fields clean, tarps cover what the storm did, and repairs gradually erase it — so documentation happens immediately. Wide shots establish the property’s condition; close-ups establish the character of the damage; everything is date-stamped, because a pile of undated photos invites a pile of questions.
A strong claim file gathers more than roof pictures:
- Date-stamped photos and video of the full exterior, the damaged slopes, and each elevation of the house
- Close-ups of soft-metal hits — gutters, downspouts, vent hoods, and air-conditioner fins are hail’s honest witnesses
- Interior photos of any leaks, plus attic shots of stained sheathing or daylight at the deck
- Saved shingle samples and any loose flashing pieces, bagged and labeled
- The local weather record for the date of loss, from the National Weather Service or a reputable archive
- All receipts for emergency mitigation, and notes on which neighbors sustained visible damage
Soft-metal dents deserve special mention because adjusters use them to confirm hail. Shingles bruise inconsistently across a weathered roof, but a clean round dent in an aluminum gutter apron tells a clear, dateable story. A contractor who inspects before the adjuster visit can flag those markers in place — and the claim file you build in week one is the version of the truth the whole process runs on.
Which Policy Details Decide Your Payout?
The biggest fork in the road is the settlement basis. A replacement cost value policy pays what it costs to replace the damaged roof with new material, typically releasing recoverable depreciation after the work is done. An actual cash value policy pays the depreciated value of the roof — its age discounted against its life — and that is the end of it. On a 15-year-old architectural roof, the difference between the two can easily be thousands of dollars out of pocket.
| Feature | ACV Policy | RCV Policy |
|---|---|---|
| First check | Full payout, minus deductible and depreciation, up front | Actual cash value of the damage, minus deductible |
| Depreciation | Withheld permanently | Withheld, then released after completion with invoices |
| Who covers the gap | You do — depreciation never returns | Nobody, if the work is completed and documented |
| Out-of-pocket result | Deductible plus years of lost value | Usually just the deductible |
| Watch for | Roof schedules that switch to ACV at a set age | Deadlines for submitting final invoices for release |
Wind/hail deductibles are the second decisive detail. Policies in storm-prone regions often set them as a percentage of dwelling coverage — commonly 1% to 5% — rather than a flat figure, which can multiply the deductible on a higher-value home. Exclusions come third: cosmetic-damage-only hail provisions, matching-shingle limitations, and wear-and-tear exclusions all shape what the insurer will pay. Knowing your own numbers turns the conversation from surprise to arithmetic.
When Should You File — and Why Does Timing Matter?
Timing decisions in insurance claims are not symmetrical. Filing early costs almost nothing and preserves every option; filing late can quietly kill a valid claim. The prompt-notice requirement is not decorative — delays give the insurer room to argue that later weather or neglect caused the damage, and they compress the window for supplements and disputes. If a claim is going to be filed at all, the answer to “when” is essentially “now.”
The one decision that deserves thought is whether the damage justifies the claim at all. If the estimate is close to or below your deductible, paying out of pocket keeps your claims record clean, and a quick call to your agent tells you how a claim of a given size would affect renewal — a conversation agents answer every day.
What Happens During the Insurance Adjuster’s Visit?
The adjuster’s visit is the central event of the claim. The adjuster walks the roof, counts squares, photographs damage, tests shingle mats for bruising, and translates it into a scope of loss — the line-item list of quantities and unit prices the insurer intends to pay. Ask for a copy as a matter of course; what gets listed is what gets paid, from ice-and-water barrier at the eaves to starter strip and ridge cap.
An adjuster’s first scope is a draft, not a verdict. The contractors who get fair payouts are the ones standing on the roof when the adjuster is, with photos ready and a ladder already set.
— Sam Construction Group USA, insurance claims & storm team
Having your own contractor present changes the quality of that inspection. A roofer who knows the assembly can point out bruising an adjuster missed, confirm decking condition, and speak to code requirements in real time. When your contractor’s estimate and the insurer’s scope disagree — missing line items, short quantities, prices below local reality — the remedy is a supplement: a formal, documented request to add what was missed. Supplements are routine, not adversarial.
What If Your Claim Is Denied or Underpaid?
A denial letter is a position statement, not a verdict. Read it against the policy: the insurer must point to the specific exclusion it is applying, and the exact language matters more than the summary above it. Damage framed as “wear and tear” is the most common battleground — dated photos, the weather record, and a contractor’s written opinion are what separate the two categories in a dispute.
Read the denial letter twice, against the policy. Insurers have to cite the exact exclusion they’re applying — and a fair number of denials soften the moment that language is examined next to real photos.
— Sam Construction Group USA, Fairfax roofing & restoration team
The escalation ladder has three main rungs. A reinspection puts a different adjuster or an engineer on the roof with your evidence in hand, and it changes outcomes often enough that no homeowner should skip it. The appraisal clause — written into most policies — lets each side name an appraiser, and those two choose an umpire to resolve a disagreement over amount. A public adjuster works for you, typically for a percentage of the recovery, and earns it on large or stubbornly contested files. Every rung has deadlines attached, which is one more reason the paper trail from week one matters.
How Do You Choose a Contractor on Your Own Terms?
After a storm, the pressure moves from the weather to the phone. Insurers may suggest their preferred contractor network, and that is fine as an option — but the choice is yours, and anti-steering rules in most states prohibit an insurer from making it seem otherwise. Local firms live on their reputations in counties they will still be working in a decade, which is a fairer test than a national franchise banner.
Two arrangements that deserve caution
- A contractor who offers to “waive your deductible” is either absorbing a real loss or inflating the invoice to cover it — in several states the practice is outright insurance fraud, with your signature on the paperwork.
- Broad assignment-of-benefits agreements hand your policy rights to the contractor, who then negotiates directly with the insurer. Narrow, itemized authorizations give a contractor what they legitimately need without surrendering the claim.
On an RCV policy, the finish line is depreciation release: once the work is complete and the final invoice goes in, the insurer releases the depreciation it held back. Track that money and submit the paperwork promptly — the final invoice triggers the last payment in the claim, and it is the easiest money to leave on the table.
Roof Insurance Claims — Frequently Asked Questions
Will filing a roof claim raise my premium?
Possibly, but a single weather-related claim usually has a modest effect compared with liability losses. Rates depend on your insurer, your state, your claims history, and local storm activity. For a small repair near your deductible, price the repair first and talk with your agent before filing.
Can my insurer require me to use its preferred contractor?
No. You have the right to choose who repairs your home, and most states enforce anti-steering rules that prohibit insurers from requiring or implying a requirement to use a specific company. Preferred networks are an option, not an obligation.
What is an assignment of benefits, and should I sign one?
An assignment of benefits transfers your policy rights to the contractor, who then deals directly with the insurer. Broad versions can leave you out of decisions and invite inflated invoicing. Narrow, itemized authorizations to perform the work and communicate with your insurer are safer, so read every form before signing.
The adjuster said the damage is wear and tear. Now what?
Wear and tear is excluded, but storm damage on an older roof is still storm damage. Gather dated photos, the weather record for the date of loss, and a contractor’s written opinion, then request a reinspection. That paper trail is what separates sudden storm damage from gradual aging.
How long does a roof insurance claim usually take?
Simple approvals can pay within a few weeks, while complex or supplement-heavy claims commonly take one to three months. Replacement-cost-value policies add a final step — depreciation release after the completed work is invoiced — so the last payment can trail the finished roof by several weeks.
File Smarter. Repair Stronger.
Sam Construction Group USA guides Northern Virginia homeowners through documentation, adjuster meetings, and complete roof replacement after storm damage. Start with a free inspection and an honest read on whether a claim is worth filing at all.
☎ (571) 373-6388This article is general information for Northern Virginia property owners and is not a quote or a statement of any specific product’s terms. Costs, lifespans, and savings vary by home, climate, and product line — always confirm specifications for your own project. Free inspections: (571) 373-6388.